📅 Published: May 2, 2026
🔄 Last Updated: August 24, 2026
Introduction
Liver cancer remains a major global health challenge, and the need for earlier detection is becoming more important as healthcare systems place greater emphasis on preventive oncology. Chronic liver conditions such as hepatitis, cirrhosis and metabolic liver disease increase the risk of liver cancer and create a continuing need for surveillance among high risk populations. This is supporting demand for imaging, blood based biomarkers and newer diagnostic technologies.
The Liver Cancer Screening Market is also changing because screening is no longer limited to conventional ultrasound and alpha fetoprotein testing. Healthcare providers are increasingly exploring advanced imaging, artificial intelligence, molecular diagnostics and liquid biopsy approaches. These technologies are creating new opportunities for diagnostic companies while also changing how screening services are delivered. The growing focus on early detection is also supporting the wider Cancer Screening Market, where advances in imaging, biomarkers and molecular diagnostics are creating new opportunities across oncology. Screening is intended to identify cancer before symptoms appear, but screening methods and their limitations need to be considered carefully. The National Cancer Institute’s guidance on liver cancer screening provides an overview of ultrasound, CT and AFP testing and explains the distinction between screening and diagnostic testing.
The commercial opportunity is closely linked to the wider growth of early cancer detection. Screening can identify suspicious changes before symptoms become severe. This can improve the opportunity for timely intervention and can reduce the clinical and economic burden associated with late stage disease. For healthcare providers and investors, the shift toward earlier detection makes screening an increasingly important part of the oncology value chain.
Liver Cancer Screening Market Overview
The Liver Cancer Screening Market covers technologies, tests and services used to identify liver cancer or suspicious liver abnormalities, particularly among people who face a higher risk of developing the disease. The market includes imaging based screening, blood based tests and emerging molecular approaches. Hospitals, diagnostic centers, cancer centers and research institutions represent important end users.
Ultrasound remains an important screening method because it is relatively accessible and can be used for routine surveillance. Alpha fetoprotein testing can provide additional information when used alongside imaging. CT and MRI are more advanced imaging methods and can support further evaluation when an abnormality is identified. Their higher cost and infrastructure requirements mean that their role differs across healthcare systems.
The next stage of Liver Cancer Screening Market development is likely to involve greater integration between these methods. Instead of relying on one test, healthcare providers can combine imaging, biomarkers and patient risk information to identify people who may require additional evaluation. Artificial intelligence can support this process by helping clinicians review images and prioritize suspicious findings.
This shift matters commercially because it broadens the market beyond individual diagnostic products. Companies can compete through imaging equipment, software, biomarkers, laboratory services and integrated diagnostic platforms. The strongest opportunities are likely to emerge where these technologies improve screening efficiency without creating excessive costs for healthcare providers.
Key Takeaways
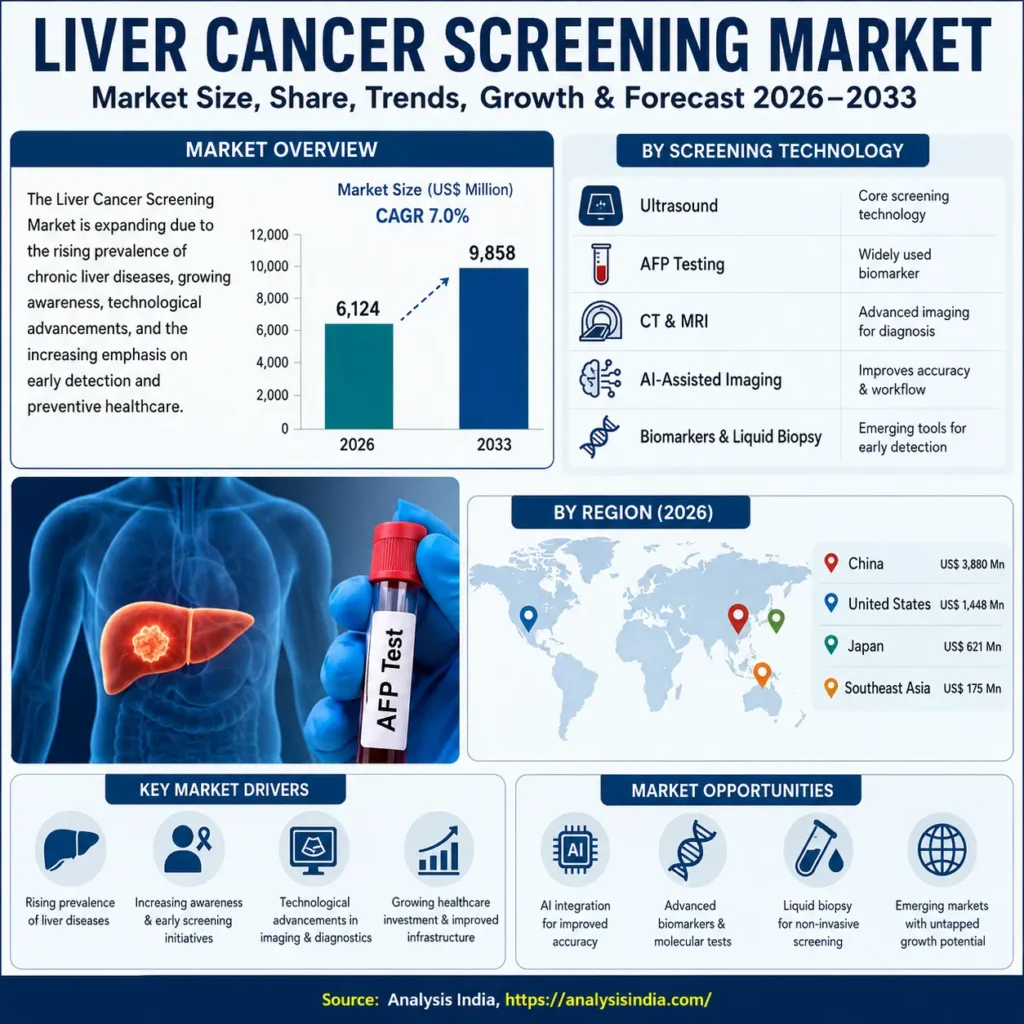
The Liver Cancer Screening Market is estimated at US$6,124 million in 2026 based on a bottom up analysis of China, the United States, Japan and Southeast Asia. The Liver Cancer Screening Market is projected to reach US$9,858 million by 2033, representing approximately 7.0% CAGR during 2026–2033.
China is the largest market within the current quantitative dataset. The United States remains an important high value market with strong adoption of advanced diagnostics. Japan represents a mature healthcare market with growing emphasis on preventive care and precision medicine. Southeast Asia is smaller in absolute value but has the fastest growth trajectory among the four markets.
Technology will remain a central factor in future Liver Cancer Screening Market development. Ultrasound and alpha fetoprotein testing will continue to support routine screening, while MRI, AI assisted imaging, biomarkers and liquid biopsy could expand the range of available screening and detection solutions.
Liver Cancer Screening Market Size and Forecast 2026–2033
The Liver Cancer Screening Market is estimated at US$6,124 million in 2026. The estimate is based on a bottom up aggregation of available market data for China, the United States, Japan and Southeast Asia. These four markets provide the quantitative foundation for the current AnalysisIndia market model.
The Liver Cancer Screening Market is projected to reach US$9,858 million by 2033. Based on the 2026 and 2033 values, the market is expected to grow at approximately 7.0% CAGR during the forecast period. This growth indicates a steady expansion rather than a short term surge. The underlying opportunity is supported by rising screening demand, greater use of advanced diagnostics and continued investment in healthcare infrastructure.
Liver Cancer Screening Market Revenue Forecast
| Year | Market Size (Million US$) |
|---|---|
| 2024 | 5,554 |
| 2025 | 5,830 |
| 2026 | 6,124 |
| 2027 | 6,517 |
| 2028 | 6,951 |
| 2029 | 7,418 |
| 2030 | 7,945 |
| 2031 | 8,510 |
| 2032 | 9,152 |
| 2033 | 9,858 |
The table shows a consistent upward trend across the forecast period. The market increases from US$5,554 million in 2024 to US$6,124 million in 2026. It then reaches US$7,945 million in 2030 before approaching US$10 billion by 2033. This trajectory suggests that demand is likely to build progressively as screening capacity expands and healthcare providers adopt more advanced diagnostic solutions.
It does not assign separate revenue estimates to Europe, India, South Korea, Australia, Latin America, the Middle East or Africa because comparable market values are not currently available in the dataset used for this analysis. These regions can still be discussed from an epidemiological and industry perspective, but they should not be given unsupported market values.
How the Bottom Up Market Estimate Is Defined
The AnalysisIndia approach uses available market values for China, the United States, Japan and Southeast Asia and combines them to create the current quantitative market base. In 2026, China contributes US$3,880 million, the United States contributes US$1,448 million, Japan contributes US$621 million and Southeast Asia contributes US$175 million. Together, these markets produce the US$6,124 million estimate.
This approach provides a transparent way to build the market model while avoiding unsupported assumptions about regions for which comparable revenue data are unavailable. It also allows the article to identify differences in Liver Cancer Screening Market scale and growth across the selected markets.
The country pages published by AnalysisIndia provide deeper analysis of China, the United States and Japan. The pillar article will therefore use country data to explain the structure of the market rather than reproduce the full country reports. This creates a clear relationship between the global pillar and its country level cluster pages.
What the Forecast Means for the Industry
The growth forecast has several implications for the healthcare industry. Diagnostic companies can benefit from rising demand for imaging systems, biomarker tests and software that supports early detection. Healthcare providers may need to expand screening capacity as the number of high risk patients requiring surveillance increases. Technology companies also have an opportunity to build tools that improve diagnostic workflows and connect imaging with clinical information.
The most important opportunity may be the integration of different screening technologies. A Liver Cancer Screening Market that combines imaging, biomarkers, artificial intelligence and patient risk assessment can create more value than a market based on individual tests alone. Over the next several years, competition is therefore likely to shift toward solutions that improve accuracy, efficiency and accessibility at the same time.
Key Growth Drivers Shaping the Liver Cancer Screening Market
The Liver Cancer Screening Market is being influenced by several structural changes in healthcare. The most important is the growing focus on detecting cancer earlier among people who have a higher risk of developing the disease. At the same time, improvements in diagnostic technology are expanding the options available to healthcare providers.
Rising Burden of Liver Cancer and Chronic Liver Disease
The growing burden of chronic liver disease is a major demand driver for screening services. Hepatitis infections, cirrhosis and metabolic liver conditions can increase the risk of liver cancer. As the number of people living with these conditions rises in several markets, healthcare providers face greater demand for regular monitoring of high risk patients.
This creates a direct link between disease prevalence and screening demand. A larger high risk population requires more imaging procedures, laboratory tests and follow up examinations. The commercial effect extends across hospitals, diagnostic centers, imaging equipment providers and laboratory testing companies.
The impact is particularly important in markets where liver cancer has a high disease burden. China represents the largest market in the current bottom up dataset. The United States also has substantial demand because of chronic liver disease and the growing importance of metabolic risk factors.
Growing Emphasis on Early Cancer Detection
Healthcare systems are increasingly placing greater value on early cancer detection. Liver cancer can develop without obvious symptoms during its earlier stages. This makes surveillance and timely investigation important for people with established risk factors.
The Liver Cancer Screening Market benefits from this shift because early detection creates demand before advanced symptoms appear. Healthcare providers can use routine surveillance to identify suspicious changes that require additional diagnostic evaluation. This can increase the use of imaging and laboratory based testing.
The commercial opportunity is therefore connected to the broader movement toward preventive healthcare. Diagnostic companies that can provide reliable and accessible screening solutions are positioned to benefit as healthcare systems place greater emphasis on earlier intervention.
The broader shift toward earlier diagnosis is consistent with the WHO cancer early detection guidance, which highlights early diagnosis and screening as important components of cancer control.
Expansion of Healthcare Infrastructure
Healthcare infrastructure is another important factor supporting Liver Cancer Screening Market development. New hospitals, diagnostic centers and specialized cancer facilities can increase access to screening services. Improvements in imaging capacity are particularly important because ultrasound, CT and MRI remain central components of liver cancer evaluation.
Infrastructure expansion can also reduce geographic barriers. In developing healthcare systems, screening may previously have been concentrated in major cities. Wider diagnostic networks can extend access to regional and semi urban populations.
This expansion creates opportunities for both established medical technology companies and newer diagnostic providers. The strongest commercial potential is likely to come from solutions that can deliver reliable results while keeping operating and equipment costs manageable.
Increasing Healthcare Awareness
Public awareness is also becoming more important. People with chronic liver conditions are more likely to seek regular medical monitoring when the importance of early detection is clearly communicated. Healthcare campaigns can therefore influence demand even when the underlying disease burden remains unchanged.
Greater awareness can also improve the utilization of existing diagnostic infrastructure. A hospital may have advanced imaging equipment, but its commercial value depends partly on whether patients and physicians use those services regularly.
For the Liver Cancer Screening Market, this means that future growth will depend not only on technology availability but also on screening participation. Healthcare providers and public health organizations therefore have an important role in converting awareness into regular surveillance.
Rising Investment in Precision Oncology
The growing use of precision oncology is adding another layer to the screening ecosystem. Precision oncology uses information about a patient’s disease and biological characteristics to support more targeted clinical decisions. In liver cancer, this approach can connect risk assessment, screening, diagnosis and subsequent treatment planning.
The Liver Cancer Screening Market can benefit when screening becomes part of a broader data driven care pathway. Biomarkers and molecular tests may help identify patients who need closer monitoring, while advanced imaging can provide additional information about suspicious lesions.
This trend also changes the competitive environment. Companies are increasingly competing on their ability to integrate diagnostic information rather than simply providing a single test. That creates opportunities for businesses developing connected imaging, laboratory and clinical decision support platforms.
Market Dynamics
The Liver Cancer Screening Market is therefore moving toward a more integrated screening model. Traditional methods remain important because they are established and accessible. However, newer technologies are gradually adding capabilities that can improve risk assessment, image interpretation and diagnostic follow up.
One important dynamic is the balance between clinical value and affordability. Advanced technologies can offer greater information, but their adoption depends on equipment costs, trained professionals, regulatory requirements and healthcare budgets. The Liver Cancer Screening Market with strong healthcare infrastructure may adopt sophisticated technologies faster, while emerging markets may continue to rely more heavily on established screening methods.
Another important dynamic is the growing role of technology companies in oncology diagnostics. AI software, digital imaging and data analytics are creating new opportunities outside traditional medical equipment manufacturing. This could make the competitive landscape more diverse as healthcare providers seek integrated solutions rather than isolated diagnostic products.
Overall, the Liver Cancer Screening Market is moving toward a model where accessibility, diagnostic performance and workflow efficiency become equally important. Companies that can combine these factors are likely to have stronger opportunities as screening systems expand through 2033.
Technology Trends in the Liver Cancer Screening Market
Technology is becoming one of the strongest forces shaping the Liver Cancer Screening Market. Established methods continue to provide the foundation for routine surveillance, but newer technologies are changing how healthcare providers identify and evaluate suspicious liver abnormalities. The Liver Cancer Screening Market is therefore moving toward a combination of imaging, laboratory testing and digital tools rather than reliance on a single screening method.
The commercial importance of this transition is significant. Healthcare providers need technologies that can support earlier detection without making screening too expensive or difficult to deliver. This creates opportunities for companies that can improve diagnostic performance while fitting into existing clinical workflows.
Ultrasound Remains a Core Screening Technology
Ultrasound remains an important screening technology because it is relatively accessible and can be used for routine surveillance. It does not expose patients to ionizing radiation and is available across a wide range of healthcare settings. These characteristics make it particularly relevant where healthcare systems need to monitor large numbers of high risk patients.
However, ultrasound also has limitations. Image quality can depend on the equipment and the experience of the operator. Patient characteristics can also affect image interpretation. These limitations create an opportunity for software and AI tools that can assist clinicians in identifying potentially suspicious findings.
For the Liver Cancer Screening Market, ultrasound is therefore likely to remain a core technology even as advanced diagnostic approaches expand. New technologies are more likely to complement routine ultrasound in the near term than completely replace it.
Alpha-Fetoprotein Testing
Alpha-fetoprotein, commonly known as AFP, is a blood based biomarker that has an established role in liver cancer surveillance. Its main commercial advantage is accessibility. Blood testing can be integrated into routine laboratory services and does not require expensive imaging equipment.
AFP also has limitations because elevated levels do not always indicate liver cancer and some liver cancers may not produce high AFP levels. For this reason, it is generally more useful when interpreted alongside imaging and other clinical information rather than used as a standalone solution.
The future role of AFP will therefore depend partly on how effectively it can be combined with other screening methods. This broader move toward multimodal screening is important for diagnostic companies because it creates demand for platforms that can combine laboratory and imaging information.
CT and MRI in Advanced Screening
CT and MRI provide more detailed imaging than conventional ultrasound and can play an important role when suspicious findings require further evaluation. MRI is particularly valuable because it can provide detailed images of soft tissue and help clinicians characterize liver lesions.
CT also remains important because it is widely available in developed healthcare systems and can provide detailed cross sectional images. However, both technologies require more expensive equipment and infrastructure than ultrasound. CT also uses ionizing radiation, while MRI can involve longer examination times and higher costs.
These factors mean that advanced imaging will not replace lower cost screening methods across all healthcare settings. Instead, the Liver Cancer Screening Market is likely to develop around a tiered diagnostic pathway. Routine surveillance can rely on accessible methods, while more advanced imaging can be used when additional assessment is required.
AI-Powered Liver Cancer Screening
Artificial intelligence is becoming an important area of innovation. AI based imaging systems can analyze medical images and identify patterns that may be difficult to detect consistently through manual review. These systems can potentially help radiologists prioritize suspicious cases and support more efficient workflows.
The commercial opportunity is broader than simply developing an algorithm. Healthcare providers need solutions that can integrate with existing imaging systems and clinical workflows. AI tools must also demonstrate reliability, clinical usefulness and regulatory compliance before they can achieve widespread adoption.
Our view is that the strongest near term opportunity for AI is likely to come from workflow support rather than replacement of clinicians. Software that helps prioritize images, identify suspicious lesions or reduce repetitive review tasks can create practical value for hospitals. This could make AI one of the more important technology growth areas through 2033.
Biomarkers and Molecular Diagnostics
Biomarker testing is expanding the role of laboratory diagnostics in liver cancer screening. Biomarkers can provide biological information that is not available from imaging alone. When combined with patient history and imaging results, this information may improve risk assessment and help identify patients who require further evaluation.
Molecular diagnostics take this approach further by examining biological signals associated with disease. Advances in genomics and molecular testing could eventually support more personalized screening strategies for high risk populations.
The commercial potential is significant, but adoption will depend on clinical validation, regulatory approval, testing costs and integration into routine healthcare. Technologies that demonstrate clear clinical value while remaining practical for laboratories are more likely to gain traction.
Liquid Biopsy and Emerging Technologies
Liquid biopsy is one of the most closely watched emerging areas in the Liver Cancer Screening Market. The approach uses a blood sample to look for biological signals associated with cancer. Its non-invasive nature makes it attractive for repeated monitoring and could potentially complement conventional imaging.
However, liquid biopsy remains an emerging technology for liver cancer screening. Greater clinical validation is required before it can become a routine component of large scale screening programs. Cost, sensitivity, specificity and regulatory requirements will also influence adoption.
The longer term opportunity is substantial if liquid biopsy can provide reliable early detection. It could make repeated surveillance easier and potentially extend screening access beyond healthcare settings that have advanced imaging infrastructure.
Technology Outlook
The technology landscape is therefore becoming more diverse. Ultrasound and AFP remain important because they are established and relatively accessible. CT and MRI provide advanced imaging capabilities, while AI can improve image analysis and workflow efficiency. Biomarkers, molecular diagnostics and liquid biopsy could add new layers of risk assessment and early detection.
The key Liver Cancer Screening Market opportunity will not necessarily come from one technology replacing another. Instead, growth is likely to come from better integration between established and emerging methods. Companies that can connect imaging, laboratory testing and digital decision support may be better positioned as healthcare providers seek more efficient screening pathways.
For the Liver Cancer Screening Market, this transition creates a broader technology ecosystem. The competitive advantage will increasingly depend on clinical evidence, usability, affordability and the ability to fit new technologies into existing healthcare systems.
Liver Cancer Screening Market Segmentation
The Liver Cancer Screening Market can be analyzed across several dimensions because screening systems differ in technology, healthcare setting and patient risk. Understanding these segments helps explain where current revenue is concentrated and where future growth could emerge. The Liver Cancer Screening Market is also becoming more integrated as healthcare providers combine imaging, laboratory testing and digital tools.
By Screening Technology
Technology remains the most important segmentation category. Established imaging and laboratory methods continue to account for a large share of screening activity, while newer approaches are gradually expanding their role.
| Screening Technology | Current Role | Growth Outlook |
|---|---|---|
| Ultrasound | Core surveillance method | Strong |
| AFP testing | Supporting biomarker test | Moderate |
| CT | Advanced imaging | Stable to moderate |
| MRI | Advanced lesion assessment | Strong |
| AI-assisted imaging | Emerging digital layer | High |
| Biomarker testing | Emerging diagnostic segment | High |
| Liquid biopsy | Emerging technology | High long-term potential |
Ultrasound is likely to remain an important part of the Liver Cancer Screening Market because of its accessibility and relatively lower cost. AFP testing can complement imaging by providing additional biological information. CT and MRI occupy a more advanced position and are particularly relevant when suspicious findings require further assessment.
AI-assisted imaging represents a different type of Liver Cancer Screening Market opportunity. It does not necessarily replace an existing screening modality. Instead, it adds a software layer that can support image interpretation and clinical workflow. This creates opportunities for technology providers without requiring healthcare systems to completely replace their existing imaging infrastructure.
Biomarkers and liquid biopsy represent longer-term opportunities. Their growth will depend on clinical validation, regulatory acceptance and cost effectiveness. If these technologies demonstrate reliable early detection, they could expand the range of screening options available to high-risk populations. The potential role of liquid biopsy extends beyond liver cancer and is part of the broader Global Liquid Biopsy Cancer Screening Market, where non-invasive testing is attracting growing research and commercial interest.
By End User: Liver Cancer Screening Market
The Liver Cancer Screening Market can also be divided by the type of healthcare organization providing screening and diagnostic services.
Hospitals represent an important end-user segment because they have access to imaging equipment, specialist physicians and laboratory services. Large hospitals can also integrate screening with oncology and hepatology services. This makes them important customers for advanced imaging systems and digital diagnostic technologies.
Diagnostic centers are another major segment. These facilities can provide imaging and laboratory testing without requiring patients to access a full hospital environment. Growth in diagnostic networks can increase screening access in areas where hospital capacity is limited.
Specialty cancer centers are particularly relevant for high-risk patients and those requiring more advanced evaluation. These centers are more likely to adopt sophisticated imaging, molecular testing and AI-supported diagnostic tools.
Research institutions represent a smaller commercial segment but have strategic importance. They help validate emerging biomarkers, molecular tests and new imaging technologies. Research activity can therefore influence future commercial adoption even when direct revenue remains limited.
By Patient Risk Profile
Risk based screening is another important dimension of the Liver Cancer Screening Market. Screening demand is not distributed evenly across the population. People with chronic liver disease, cirrhosis or certain viral hepatitis infections may require closer surveillance than people without these risk factors.
Metabolic liver disease is also becoming increasingly relevant. Conditions associated with obesity and metabolic disorders can contribute to chronic liver damage and increase the importance of monitoring at-risk populations.
This creates a Liver Cancer Screening Market opportunity that is closely connected to the management of chronic disease. As healthcare systems improve identification of high-risk patients, screening can become more targeted and regular. The result is a more predictable demand base for imaging and laboratory services.
By Geography: Liver Cancer Screening Market
Geography is particularly important because Liver Cancer Screening Market maturity differs significantly across healthcare systems. Some markets have advanced imaging infrastructure and established screening pathways, while others are still expanding basic diagnostic access.
The current AnalysisIndia bottom-up model uses four quantified markets: China, the United States, Japan and Southeast Asia. These Liver Cancer Screening Market together form the quantitative base of the 2026–2033 forecast.
China represents the largest market within this dataset. The United States is an important high-value market with advanced diagnostic infrastructure. Japan represents a mature healthcare Liver Cancer Screening Market with strong technology adoption. Southeast Asia has a smaller market base but a faster growth trajectory.
This geographic segmentation also shows why a single global growth rate does not tell the complete story. The Liver Cancer Screening Market size, healthcare infrastructure, disease burden and technology adoption can vary substantially between regions.
Segmentation Outlook
The Liver Cancer Screening Market is likely to become more integrated across these segments. Imaging will continue to provide the core diagnostic foundation, while biomarkers, AI and molecular technologies add new capabilities.
From a business perspective, the strongest opportunities may emerge where technologies complement each other. A company that can connect imaging with laboratory data and digital decision support may create more value than one offering an isolated diagnostic product.
Regional Analysis of the Liver Cancer Screening Market
The geographic structure of the Liver Cancer Screening Market is uneven. Market size depends on disease burden, healthcare infrastructure, screening practices and access to advanced diagnostic technologies. The current AnalysisIndia bottom up model covers China, the United States, Japan and Southeast Asia because comparable market values are available for these markets.
Together, these four Liver Cancer Screening Market reach US$6,124 million in 2026 and are projected to reach US$9,858 million by 2033. The comparison also shows that market leadership and growth leadership are not the same. China has the largest market by value, while Southeast Asia has the fastest growth trajectory in the available dataset.
Selected Market Comparison: Liver Cancer Screening Market
| Market | 2024 | 2026 | 2033 | 2026–2033 CAGR |
|---|---|---|---|---|
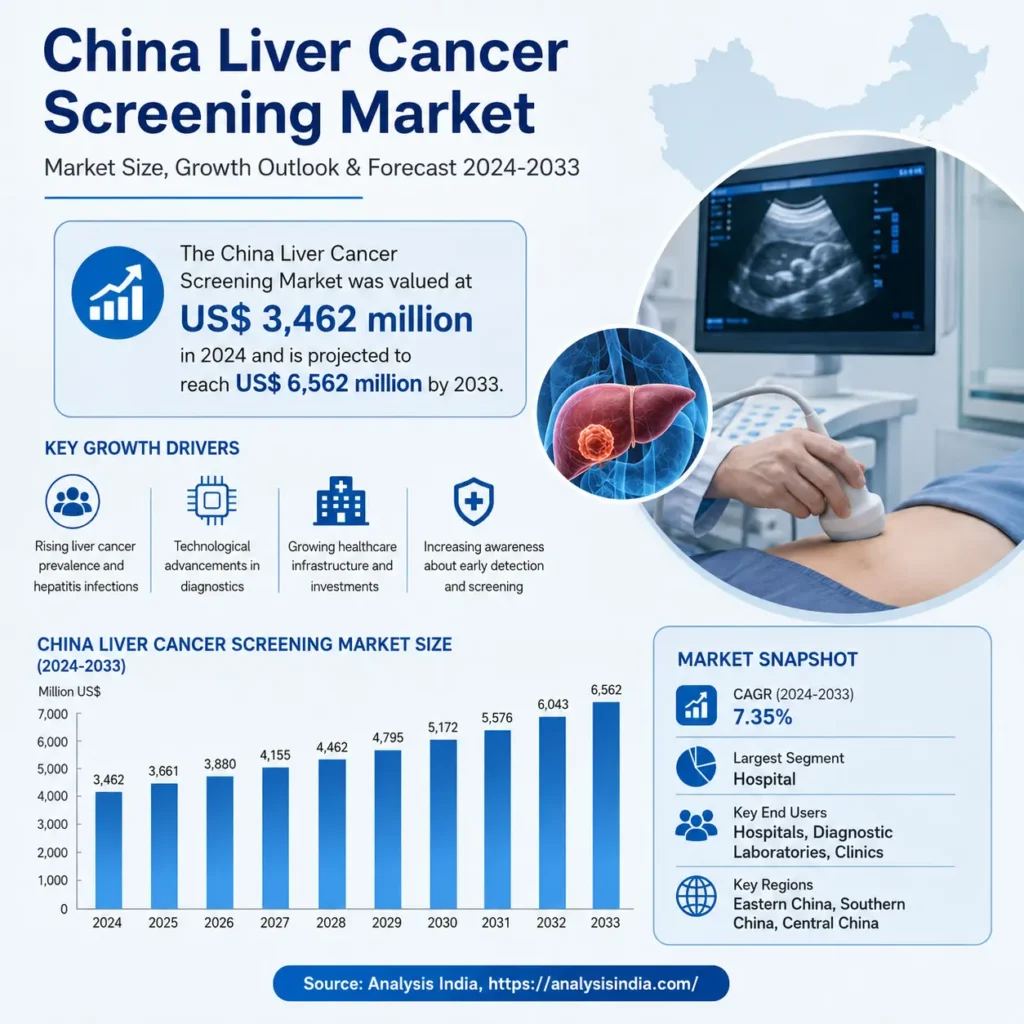
| China | 3,462 | 3,880 | 6,562 | 7.8% |
| United States | 1,336 | 1,448 | 2,158 | 5.9% |
| Japan | 608 | 621 | 744 | 2.6% |
| Southeast Asia | 148 | 175 | 394 | 12.3% |
| Combined | 5,554 | 6,124 | 9,858 | 7.0% |
Market values are in Million US$. CAGR is calculated from the 2026 and 2033 values.
China Leads the Liver Cancer Screening Market by Scale
China is the largest market in the current quantitative model. Its market is estimated at US$3,880 million in 2026 and is projected to reach US$6,562 million by 2033. This makes China the largest contributor to the combined market throughout the forecast period.
The scale of the Chinese market is linked to its large population, liver cancer burden and expanding healthcare infrastructure. Growing access to advanced imaging and diagnostic services is also creating opportunities for technology providers.
China’s position is important for companies operating in imaging, biomarkers, AI-assisted diagnostics and laboratory testing. However, the market is not uniform across the country. Differences in healthcare access and infrastructure between major urban centers and less developed areas can influence technology adoption.
The dedicated China Liver Cancer Screening Market article provides a deeper analysis of these country-specific factors.
United States Remains a High Value Market
The United States represents the second largest market in the current model. The United States Liver Cancer Screening Market is estimated at US$1,448 million in 2026 and is projected to reach US$2,158 million by 2033.
The US market has a different structure from China. Its importance comes not only from market size but also from its advanced healthcare infrastructure and strong adoption of sophisticated diagnostic technologies. Hospitals and specialist centers have greater access to advanced imaging, laboratory testing and digital healthcare systems.
Artificial intelligence and precision medicine are likely to remain important areas of development. The commercial opportunity is particularly relevant for companies offering technologies that can integrate into established clinical workflows.
The dedicated United States Liver Cancer Screening Market analysis provides further detail on the country’s healthcare environment and technology adoption.
Japan Represents a Mature Innovation Market
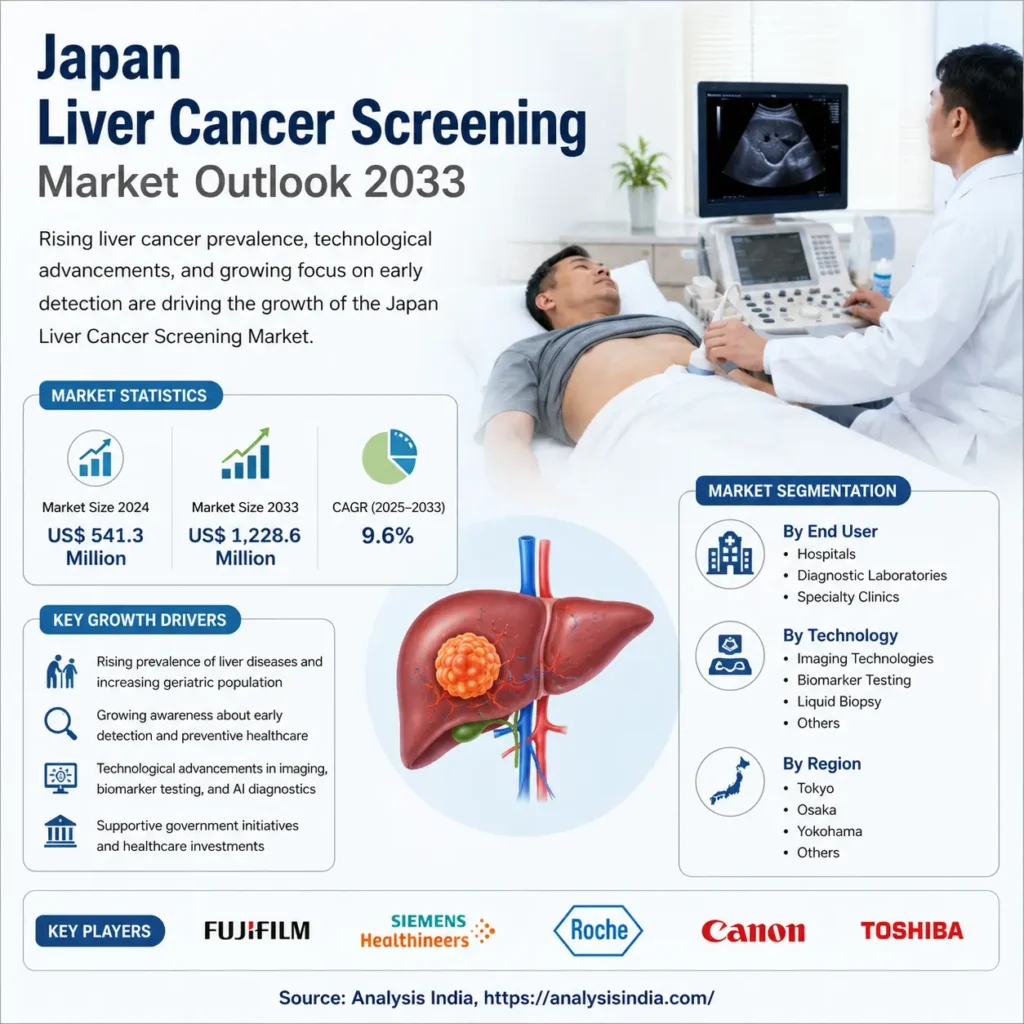
Japan is estimated at US$621 million in 2026 and is projected to reach US$744 million by 2033. Its growth rate is lower than the other three markets, but this does not mean that Japan lacks strategic importance.
Japan has a mature healthcare system and strong demand for advanced medical technologies. Its aging population also creates continued demand for preventive healthcare and chronic disease management. These conditions support the use of sophisticated imaging, biomarkers and precision diagnostic approaches.
For technology companies, Japan can therefore be viewed less as a high volume expansion market and more as an innovation focused market. The country’s healthcare environment can support adoption of advanced solutions where clinical value is clearly demonstrated.
The dedicated Japan Liver Cancer Screening Market article covers these country-specific trends in greater detail.
Southeast Asia Shows the Fastest Growth
Southeast Asia is the smallest market in the current model, with an estimated value of US$175 million in 2026. However, it is projected to reach US$394 million by 2033.
This represents approximately 12.3% CAGR between 2026 and 2033, making Southeast Asia the fastest growing market among the four quantified markets.
The difference between market size and growth rate is strategically important. Southeast Asia does not currently match China or the United States in absolute market value. However, its faster expansion suggests that improving healthcare infrastructure, wider diagnostic access and increasing awareness could create significant opportunities for screening providers.
For investors and healthcare technology companies, this market may therefore offer a different type of opportunity. China provides scale, while Southeast Asia provides higher growth potential from a smaller base.
China Leads Scale While Southeast Asia Leads Growth
The geographic data reveal an important pattern in the Liver Cancer Screening Market.
China accounts for the largest share of the current four-market market base. In 2026, its US$3,880 million market represents approximately 63% of the combined US$6,124 million. By 2033, China’s share rises to approximately 67% of the combined market.
Southeast Asia follows the opposite pattern. Its market remains relatively small, but it grows from US$175 million in 2026 to US$394 million in 2033. This makes it the fastest-growing market in the current dataset.
The United States occupies an important middle position. It combines substantial market value with a strong technology base. Japan has the slowest growth rate among the four markets, but its mature healthcare system supports demand for advanced diagnostic solutions.
This suggests that companies should not evaluate geographic opportunities using market size alone. Scale, growth rate, technology adoption and healthcare maturity can lead to very different investment opportunities.
The current model does not assign market values to Europe, India, South Korea, Australia, Latin America, the Middle East or Africa because comparable figures are not included in the underlying dataset. These markets can still be important from a disease burden and healthcare development perspective, but assigning unsupported revenue estimates would weaken the reliability of the pillar.
Competitive Landscape and Market Opportunities
The Liver Cancer Screening Market is becoming more competitive as healthcare providers adopt a wider range of imaging, laboratory and digital technologies. Competition is no longer limited to manufacturers of traditional diagnostic equipment. Companies working in artificial intelligence, biomarkers, molecular diagnostics and healthcare software are also becoming part of the broader screening ecosystem.
This shift is important because future market growth will depend on how effectively different technologies work together. Healthcare providers are looking for solutions that can improve early detection while fitting into existing clinical workflows. Companies that can demonstrate measurable clinical value and practical integration may therefore have stronger opportunities than providers offering isolated technologies.
Imaging Companies Remain Central to the Market
Imaging remains the foundation of liver cancer surveillance and diagnostic evaluation. Ultrasound continues to have an important role because of its accessibility and established use. CT and MRI provide more detailed imaging and are particularly relevant when suspicious findings require further assessment.
For imaging manufacturers, the opportunity extends beyond selling individual systems. Software integration, image analysis and workflow support are becoming increasingly important. Hospitals want to improve the value of existing equipment rather than replace systems every time a new technology becomes available.
This creates an opportunity for manufacturers that can combine hardware with digital capabilities. AI-assisted image interpretation can add another layer of value to imaging systems while helping healthcare providers manage increasing diagnostic workloads.
AI Creates a New Competitive Layer
Artificial intelligence is introducing a new competitive dimension to the Liver Cancer Screening Market. Traditional competition has largely focused on equipment performance, image quality and laboratory accuracy. AI introduces competition based on algorithms, software integration, data management and clinical decision support.
AI systems can potentially help identify suspicious liver lesions and prioritize cases for further review. They can also support radiologists by reducing repetitive image analysis tasks. However, commercial adoption depends on more than technical performance.
Healthcare providers need evidence that AI tools improve clinical workflows and produce reliable results. Regulatory approval, interoperability and ease of integration will also influence purchasing decisions.
The strongest opportunity may therefore lie in AI-enabled diagnostic workflows rather than standalone AI products. This approach allows hospitals to use AI alongside existing imaging systems and clinical expertise.
Biomarkers and Molecular Diagnostics Expand the Opportunity
Biomarker and molecular diagnostic companies can benefit from the growing interest in more personalized screening. These technologies can provide information that complements conventional imaging and may help clinicians identify patients who need additional assessment.
The commercial opportunity is particularly relevant for companies developing tests that can be incorporated into routine laboratory workflows. Ease of use and cost will be important because screening programs often need to monitor large populations.
Molecular diagnostics also create opportunities beyond traditional screening. As healthcare systems adopt precision oncology, diagnostic information may increasingly be used across the patient journey. This could connect screening with risk assessment, diagnosis and treatment planning.
Investment Opportunities
The expanding Liver Cancer Screening Market creates opportunities across several parts of the healthcare value chain.
AI assisted imaging is one of the most promising areas because it can add software capabilities to established diagnostic infrastructure. Companies that improve image interpretation, workflow prioritization and clinical decision support could benefit as healthcare providers seek greater efficiency.
Biomarker testing represents another opportunity. Better biomarkers could strengthen the ability to identify high risk patients and complement imaging based surveillance. The main investment consideration will be whether new tests can demonstrate sufficient clinical value to justify their cost.
Liquid biopsy has longer term potential. Its non-invasive nature could make it attractive for repeated monitoring if clinical validation supports broader use. However, investors should distinguish between technological potential and established commercial adoption.
Healthcare infrastructure also presents opportunities in developing markets. Expansion of diagnostic centers and imaging capacity can increase access to screening services. Companies able to offer cost effective solutions may benefit as healthcare systems expand beyond major urban centers.
Business Implications
For healthcare executives, the market’s expansion creates a need to evaluate screening as an integrated service rather than a collection of individual tests. Investment decisions should consider equipment utilization, workforce requirements, diagnostic accuracy and total operating costs.
For investors, technology maturity is an important consideration. Established imaging technologies offer a more mature revenue base, while AI, biomarkers and liquid biopsy provide higher potential but also greater clinical and regulatory uncertainty.
For diagnostic companies, partnerships may become increasingly important. Collaboration between imaging manufacturers, software developers, biotechnology companies and healthcare providers can accelerate the development of integrated screening solutions.
The Liver Cancer Screening Market is therefore developing into a broader technology ecosystem. Competitive advantage will increasingly depend on clinical evidence, affordability, interoperability and the ability to improve the overall screening pathway rather than simply offering a new diagnostic product.
Challenges and Future Outlook
The Liver Cancer Screening Market has strong growth potential, but expansion will not be uniform across healthcare systems. The availability of screening technology does not automatically guarantee widespread use. Cost, infrastructure, clinical expertise and patient participation can all affect how quickly new screening solutions are adopted.
Key Market Challenges
Access to screening remains a major challenge. Advanced imaging and specialized diagnostic services are concentrated in areas with stronger healthcare infrastructure. Patients in underserved regions may have fewer opportunities for regular surveillance. Expanding diagnostic networks will therefore be important for converting technological progress into broader screening coverage.
Cost is another constraint. Ultrasound and basic laboratory testing can be relatively accessible, but advanced imaging, molecular diagnostics and emerging technologies can require significant investment. Healthcare providers must balance diagnostic value with equipment costs, staffing requirements and operating expenses.
Clinical workforce availability can also limit adoption. Advanced imaging requires trained professionals who can interpret results accurately. AI can support clinicians, but it does not remove the need for appropriate medical expertise and clinical oversight.
Regulatory and clinical validation requirements are particularly important for emerging technologies. Biomarkers, AI systems and liquid biopsy solutions need reliable evidence before they can become part of routine screening pathways. This can lengthen commercialization timelines and increase development costs.
Emerging Trends Through 2033
Several trends are likely to shape the Liver Cancer Screening Market through 2033. AI assisted imaging should become more closely integrated with existing diagnostic workflows. Rather than replacing established technologies, AI is more likely to improve image review, case prioritization and workflow efficiency.
Biomarker and molecular testing should also receive greater attention. Advances in laboratory diagnostics could help healthcare providers identify high risk patients and combine biological information with imaging results.
Liquid biopsy represents a longer term opportunity. If clinical evidence continues to strengthen, blood based testing could become an additional tool for repeated monitoring. Its potential is particularly important because non-invasive testing could make regular surveillance easier.
Another important trend is the integration of different diagnostic technologies. Healthcare providers are increasingly looking for connected solutions that combine imaging, laboratory data and clinical information. This could create a more coordinated screening pathway and improve the value of individual diagnostic technologies.
AnalysisIndia Outlook
Our view is that the next phase of Liver Cancer Screening Market growth will depend less on the expansion of individual diagnostic products and more on the integration of screening technologies.
The market is moving toward a model in which ultrasound, biomarkers, advanced imaging and digital tools work together. AI can help manage growing diagnostic workloads, while laboratory technologies can add biological information to imaging based assessment. This combination could improve screening efficiency while creating new commercial opportunities across the healthcare value chain.
The geographic data also provide an important signal. China is the scale leader, while Southeast Asia is the growth leader within the four-market dataset used for this analysis. The United States offers a large market with strong technology adoption, while Japan represents a mature market where advanced diagnostic innovation remains important.
The Liver Cancer Screening Market should therefore be viewed as a gradually expanding healthcare technology ecosystem rather than a single diagnostic segment. Companies that can demonstrate clinical value, control costs and integrate their solutions into existing healthcare workflows are likely to be better positioned through 2033.
Conclusion: Liver Cancer Screening Market Outlook to 2033
The Liver Cancer Screening Market is entering a period of steady expansion as healthcare systems place greater emphasis on early cancer detection and surveillance of high risk populations. Based on the bottom up market model used in this analysis, the market is estimated at US$6,124 million in 2026 and is projected to reach US$9,858 million by 2033, representing approximately 7.0% CAGR during the forecast period.
The market’s growth is supported by the continuing need to monitor people affected by chronic liver disease, cirrhosis and other risk factors. Established methods such as ultrasound and alpha fetoprotein testing will remain important, while MRI, biomarkers, AI assisted imaging and molecular diagnostics can expand the range of available screening solutions.
The geographic outlook also shows different types of opportunity. China remains the largest market in the current dataset, while Southeast Asia records the fastest growth trajectory. The United States combines significant market value with advanced diagnostic infrastructure, while Japan represents a mature market with strong interest in preventive healthcare and diagnostic innovation.
The next stage of development will depend on how effectively healthcare providers integrate different technologies. AI can support imaging workflows, biomarkers can complement conventional screening and emerging liquid biopsy technologies could create new opportunities if clinical validation continues to improve. For businesses and investors, the strongest opportunities are likely to come from solutions that combine clinical value, affordability and practical integration.
Frequently Asked Questions: Liver Cancer Screening Market
What is the Liver Cancer Screening Market size in 2026?
The Liver Cancer Screening Market is estimated at US$6,124 million in 2026 based on AnalysisIndia’s bottom up model covering China, the United States, Japan and Southeast Asia. The model uses available comparable market data for these selected markets.
How big will the market be by 2033?
The market is projected to reach approximately US$9,858 million by 2033. Based on the 2026 and 2033 estimates, the market is expected to grow at about 7.0% CAGR during the forecast period.
What is driving the growth of the Liver Cancer Screening Market?
Growth is being supported by the rising need for early cancer detection, chronic liver disease surveillance, healthcare infrastructure expansion and wider adoption of advanced diagnostic technologies. AI assisted imaging, biomarkers and molecular diagnostics are also creating new opportunities.
Which country has the largest market?
China has the largest market among the four markets included in the current quantitative model. Its market is estimated at US$3,880 million in 2026 and is projected to reach US$6,562 million by 2033.
Which market is growing fastest?
Southeast Asia is the fastest growing market among the four selected markets. Its value is estimated at US$175 million in 2026 and is projected to reach US$394 million by 2033. This represents approximately 12.3% CAGR over the period.
What technologies are used for liver cancer screening?
Common technologies include ultrasound, alpha fetoprotein testing, CT and MRI. Emerging approaches include AI assisted imaging, advanced biomarkers, molecular diagnostics and liquid biopsy. The role of each technology varies according to clinical requirements, healthcare infrastructure and cost.
How is AI changing liver cancer screening?
AI can support image analysis by helping clinicians identify suspicious lesions and prioritize cases for further review. Its near term value is more likely to come from improving workflow efficiency and supporting healthcare professionals than replacing clinical judgment.
What role could liquid biopsy play in the future?
Liquid biopsy could provide a non-invasive approach for monitoring and detecting biological signals associated with liver cancer. Its long term opportunity is significant, but wider adoption will depend on clinical validation, accuracy, cost and regulatory acceptance.
What are the major challenges facing the market?
Key challenges include unequal access to screening, high costs for advanced technologies, shortages of trained professionals and the need for clinical validation of emerging solutions. Regulatory requirements can also increase the time and investment needed to commercialize new diagnostic technologies.